Who controls the internet when your agent does the choosing? →
Current answer · Explainer
Control over access to buyers can affect who retains the gains from cheaper production.
Customers, producers or intermediaries can capture the benefit. Lower costs help a seller only if price, demand and access leave enough of the saving with that seller. A durable advantage depends on something buyers value and cannot easily get elsewhere.
Current answer · Explainer
Following covers this question’s published contributions. It does not follow neighbouring questions or subscribe you to email.
Cheaper production, tougher competition. Follow the money through a small business—and change the assumptions yourself.
An economic explanation with a fictional accounting model. No market forecast or Atlas business experiment.
Article version history → Who gets the AI saving?These narrower questions are not promises of a future article.
Comparable business outcomes over time, including prices, quantities, review costs and channel dependence; current benchmark trends alone cannot settle the question.
See the limits of this answer →Question versions describe its framing, published contributions and place in the map. Article versions keep their own evidence and history.
A new question separates falling AI costs from the returns received by customers, producers and intermediaries.
See this change across Atlas →Original article history and evidence
This history comes from saved content versions. A new revision can be an editorial change; it does not by itself mean that the underlying facts changed.
Separates cheaper AI capability from business returns, following a fictional supplier brief through price, competition and distribution.
No earlier reviewed assessment is available to compare. No change in the underlying facts is being claimed.
Separates cheaper AI capability from business returns, following a fictional supplier brief through price, competition and distribution.
Observe accepted prices, full delivery costs, repeat demand and access to buyers as comparable competitors adopt similar tools.
Comparable business outcomes over time, including prices, quantities, review costs and channel dependence; current benchmark trends alone cannot settle the question.
Customers, producers or intermediaries can capture the benefit. Lower costs help a seller only if price, demand and access leave enough of the saving with that seller. A durable advantage depends on something buyers value and cannot easily get elsewhere.
An economic explanation with a fictional accounting model. No market forecast or Atlas business experiment.
Epoch estimates a roughly 13-fold annual cost decline since 2023.
Five primary benchmarks; estimated frontier, not an enterprise cost forecast.
The Kenyan trial found no statistically detectable average improvement in revenues and profits.
640 entrepreneurs, 2023 GPT-4 advice, self-reported outcomes; effects varied by baseline performance.
More AI-exposed Upwork occupations saw lower employment and earnings after the early model launches.
Observational short-run comparison within one platform; no general wage or price forecast.
Teece explains how returns can accrue to owners of complementary assets.
Depends on imitation and access to specialized complements; a theory, not an AI market result.
Dierickx and Cool link durable advantage to the difficulty of imitating or substituting accumulated assets.
Asset erosion matters; age alone establishes neither usefulness nor advantage.
Imagine a small firm that helps specialist buyers compare suppliers. Its briefs combine document research, capability comparisons and checked claims. A better AI service makes the preparation much faster. Work that once needed several people may become viable for one specialist.
Now give every competing analyst the same tool. Give it to the buyer, too. The firm’s cost can fall while its customers become less willing to pay for the report. Whether the business improves depends on what happens between those two changes.
This is the strategic question behind cheap AI: what will still make someone buy from you when producing a plausible alternative becomes easy? Follow one fictional brief through its costs, selling price and route to the customer.
Epoch AI’s September 2026 analysis estimates rapid cost reductions at fixed benchmark performance. It supports the premise that access to some capabilities is becoming cheaper; it does not establish a universal price for intelligence.
For our supplier brief, the relevant bill also includes acquiring evidence, resolving contradictions, reviewing the result and maintaining the service. If generation accounts for only a small share, a dramatic model-price decline can produce a modest saving in the finished brief. If review increases, even that saving can disappear.
13×Estimated yearly cost decline at fixed benchmark performance since 2023: a factor of 13.
Five primary benchmarks, using the cheapest available models at each point. A historical estimate, not a business bill or a forecast.
Epoch compares the cheapest available routes to a given accuracy across models and inference budgets. Benchmarks may reward training for the test, and actual users do not continually switch to the cheapest model.
In the first case below, preparation becomes cheaper and the seller keeps the price. In the second, competition pushes the price down further than the production saving. In the third, a platform also charges for access to buyers. These are deliberately different assumptions, not stages that every market must pass through.
Contribution is what remains from each sale after preparation, checking and platform fees, before monthly fixed costs. Move the controls. The accounting always balances, including when the seller loses contribution. What it cannot tell you is which price the market will accept, how many buyers will appear, or whether a platform earns its fee by bringing additional demand.
A fictional specialist sells a supplier brief for USD 100. Preparing it costs $40 and checking it costs $20. Fixed costs are $2,000 a month. Start with no platform fee.
Preparation falls from $40 to $8. With the price unchanged, contribution rises from $40 to $72 per brief.
The saving is accounted for by these three changes
$32 saving = $0 customer saving + $0 platform receipts + $32 seller change
Invented amounts, not a forecast or an Atlas business test. Quality, verification and fixed costs stay constant. Contribution is before fixed costs; platform receipts are not platform profit. Required sales are a threshold, not predicted demand.
All amounts are USD. Baseline per brief: price $100, preparation $40, verification $20, platform fee $0. Fixed monthly cost: $2,000.
Contribution = selling price − preparation − verification − platform fee. The fee is a percentage of selling price. Break-even volume = fixed monthly cost ÷ positive contribution, rounded up to whole briefs. Preparation includes labour and tools. Verification and fixed costs stay constant; quantity and quality changes are not modelled.
| Case | Cost cut | Price | Fee | Contribution | Briefs / month |
|---|---|---|---|---|---|
| Keep the price | 80% | $100 | 0% | $72 | 28 |
| Price competition | 80% | $60 | 0% | $32 | 63 |
| Pay for access | 80% | $60 | 30% | $14 | 143 |
Keep the price: Preparation falls from $40 to $8. With the price unchanged, contribution rises from $40 to $72 per brief.
Price competition: The same cost reduction, but the selling price falls to $60. The customer saves $40; the seller’s contribution falls to $32.
Pay for access: Keep the $60 price and add a platform fee of 30%. The platform receives $18; the seller retains $14 before fixed costs.
At the original $40 contribution per brief, 50 monthly sales cover the fictional firm’s $2,000 fixed costs. Cutting preparation cost while retaining the price lowers that threshold to 28. That can make a previously uneconomic niche worth serving.
But the threshold becomes 63 briefs under the lower selling price, and 143 with the platform fee. A smaller team may still need more sales to cover its costs. Nor does a threshold establish that enough demand exists.
The buyer’s alternative matters as much as the competitor’s. If a customer can prepare an adequate comparison internally, the seller must supply something beyond a document: unusually good evidence, a consequential judgement, access or help acting on the result. The customer may instead spend the saving elsewhere. A business can become less profitable while customers become better off.
A useful small firm does not need permanent protection from competitors. Serving a modest market reliably can be enough. The question is whether the achievable price and repeat demand cover all the work, including the owner’s time.
An early Upwork study by Xiang Hui, Oren Reshef and Luofeng Zhou compared more and less AI-exposed occupations. After ChatGPT’s launch, the more exposed group had approximately 2% fewer monthly jobs and 5.2% lower monthly earnings relative to the comparison group. This observational, short-run platform result is not a measure of hourly prices or economy-wide employment. It shows why easier production cannot stand in for evidence of higher seller income.
A randomized trial with 640 Kenyan entrepreneurs offers another warning against a single business-benefit story. Participants received GPT-4 business advice over WhatsApp during roughly five months in 2023. Nicholas Otis and colleagues found no statistically detectable average improvement in self-reported revenues and profits, with effects differing by initial business performance. Their analysis points towards differences in which advice people implemented; that mechanism was not separately randomized.
The studies do not measure our fictional market or prove that competition absorbs AI savings. They ask different questions in different settings. Together they underline why a business claim needs evidence of the promised economic outcome. Access to a tool or a faster task does not establish that outcome.
David Teece’s work on profiting from innovation explains why the producer of a useful invention may not capture its returns. Commercial success can depend on complementary assets such as distribution or service. Where those assets are specialized and difficult to access, their owners may have bargaining power. This is a strategic framework developed long before generative AI, not a prediction that today’s platforms must win.
For our specialist, consider three different dependencies. Buyers might need observations that are absent from public documents. They might trust a particular analyst’s judgement under uncertainty. Or they might only discover suppliers through one purchasing platform. Each points to a different potential recipient of payment.
Now ask whether the customer has a good alternative. Public data with many good substitutes may command little premium. A platform facing easy switching may struggle to maintain its fee. A trusted specialist whose advice stops improving decisions can lose customers. Calling something scarce does not show that it is valuable, and calling it valuable does not show that you control the return.
Ingemar Dierickx and Karel Cool distinguish assets accumulated through sustained activity from resources that can simply be bought. Assets that are hard to imitate or replace can support an advantage; they can also lose their value. This gives a more precise version of the claim that time will matter when AI can generate abundant content.
Our analyst might retain dated predictions, later outcomes and corrections. A buyer could inspect whether the advice worked in comparable situations. Producing another polished report does not recreate those past observations. But an archive of confident claims with no outcomes establishes little. A long history of poor work is no advantage.
The mechanism has conditions: the record must be authentic, relevant to the next decision and useful to the buyer. Where feedback arrives slowly, honest uncertainty may matter more than a large scorecard. Relationships also need continuing service. They can deteriorate, migrate or become irrelevant.
Build the activity that produces the asset: keep predictions before outcomes are known, record failures alongside successes, and make corrections inspectable. Then test whether customers actually use the record when choosing. That is stronger than assuming that age, a community or a human signature automatically deserves a premium.
The illustration holds quality and verification constant and calculates a sales threshold. A real market can respond in other ways. Lower prices may bring in customers who could never afford the service. Better analysis may make the same brief worth more. A platform fee may buy enough additional sales to raise total profit even as contribution per brief falls.
AI could also make previously scarce complements easier to reproduce: finding a specialist, comparing providers or organizing evidence. In that case, the apparent advantage moves again. Conversely, if checking quality becomes harder, trusted evaluation may become more useful. Which effect dominates requires observation.
For the specialist, the next test is a small set of paid engagements with the full cost recorded. Track accepted prices, reasons for choosing, repeat demand, preparation and correction time, and acquisition costs by channel. Compare similar jobs and retain unsuccessful offers. Those observations can distinguish a production gain from a business gain.
The useful question is not how much more the firm can generate. It is what customers still need, why they choose this provider, and whether serving them leaves enough to continue. Cheap AI changes the possibilities. Competition and ownership help determine who can keep the proceeds.
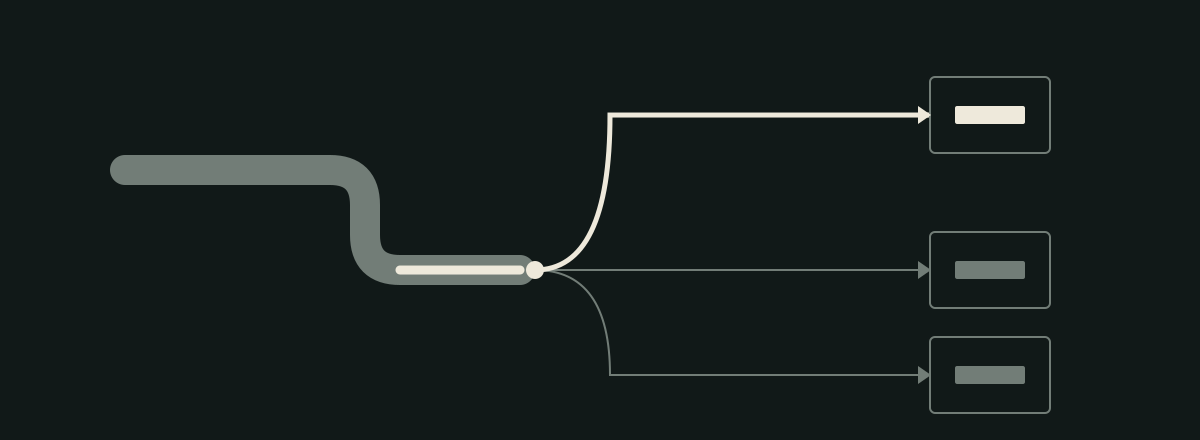
Lower production cost opens several paths for the saving. The paths are conceptual, not proportional data.
Teece explains how returns can accrue to owners of complementary assets.
Scope and conditions: Depends on imitation and access to specialized complements; a theory, not an AI market result.
Commercialization may require assets the innovator does not control.
Abstract; section 3.3 and complementary-asset analysis About the source and its versionA retrospective selection: publications used in this question and its discovery, ordered by their publication dates. This is a small historical overview, not a complete account of the field or evidence of a research trend.
Original source checked; application to the fictional business is Atlas interpretation.
Original abstract checked. Asset accumulation, imitation, substitution and erosion; not an empirical claim about AI firms.
Published abstract and authors’ October 2024 manuscript checked. Early post-launch Upwork outcomes, not the whole labour market.
Published version; experiment ran May–November 2023. Methods, results and implementation analysis checked.
Key takeaways, Table 1 and Limitations checked. Estimated cheapest model frontier, not observed business savings.